One flat fee. £9.99 a month.
We want to give you simplicity and transparency in pricing, because a fee you don't understand is a fee you shouldn't pay. Underlying fund charges (around 0.25%) may also apply.
Your capital is at risk. The value of your investments can go down as well as up. Stocks & Shares ISAs only, for now.
Financial Health Check
Start with no fee.
Try how investing with Investwizz works using mock portfolios, so you can test whether your goals are achievable — before committing a penny.
- One wealth projection
- Limited Digital copilot features
- Goal setting & basic tracking
- Interactive goal planning
Core
Fee charged on day 60. Covers you for first 3 months. Renews at £9.99/mo. Underlying fund charges (around 0.25%) may also apply.
One simple monthly subscription fee.
- Full Digital copilot
- Trading in a Stocks & Shares ISA
- Up to 3 real-money portfolios
- Two wealth projections
- Goal health monitoring
- Rebalancing nudges
Plus
In development
One simple monthly subscription fee.
- Multi-account support
- Unlimited portfolios
- Proactive monitoring & alerts
- Priority support
Build your plan and only pay when you're ready to invest. Cancel anytime. Underlying fund charges of around 0.25% apply, as with any investment. Your capital is at risk and the value of your investments can fall as well as rise.
Cash ISAs are changing
from April 2027. Here's
what you need to know.
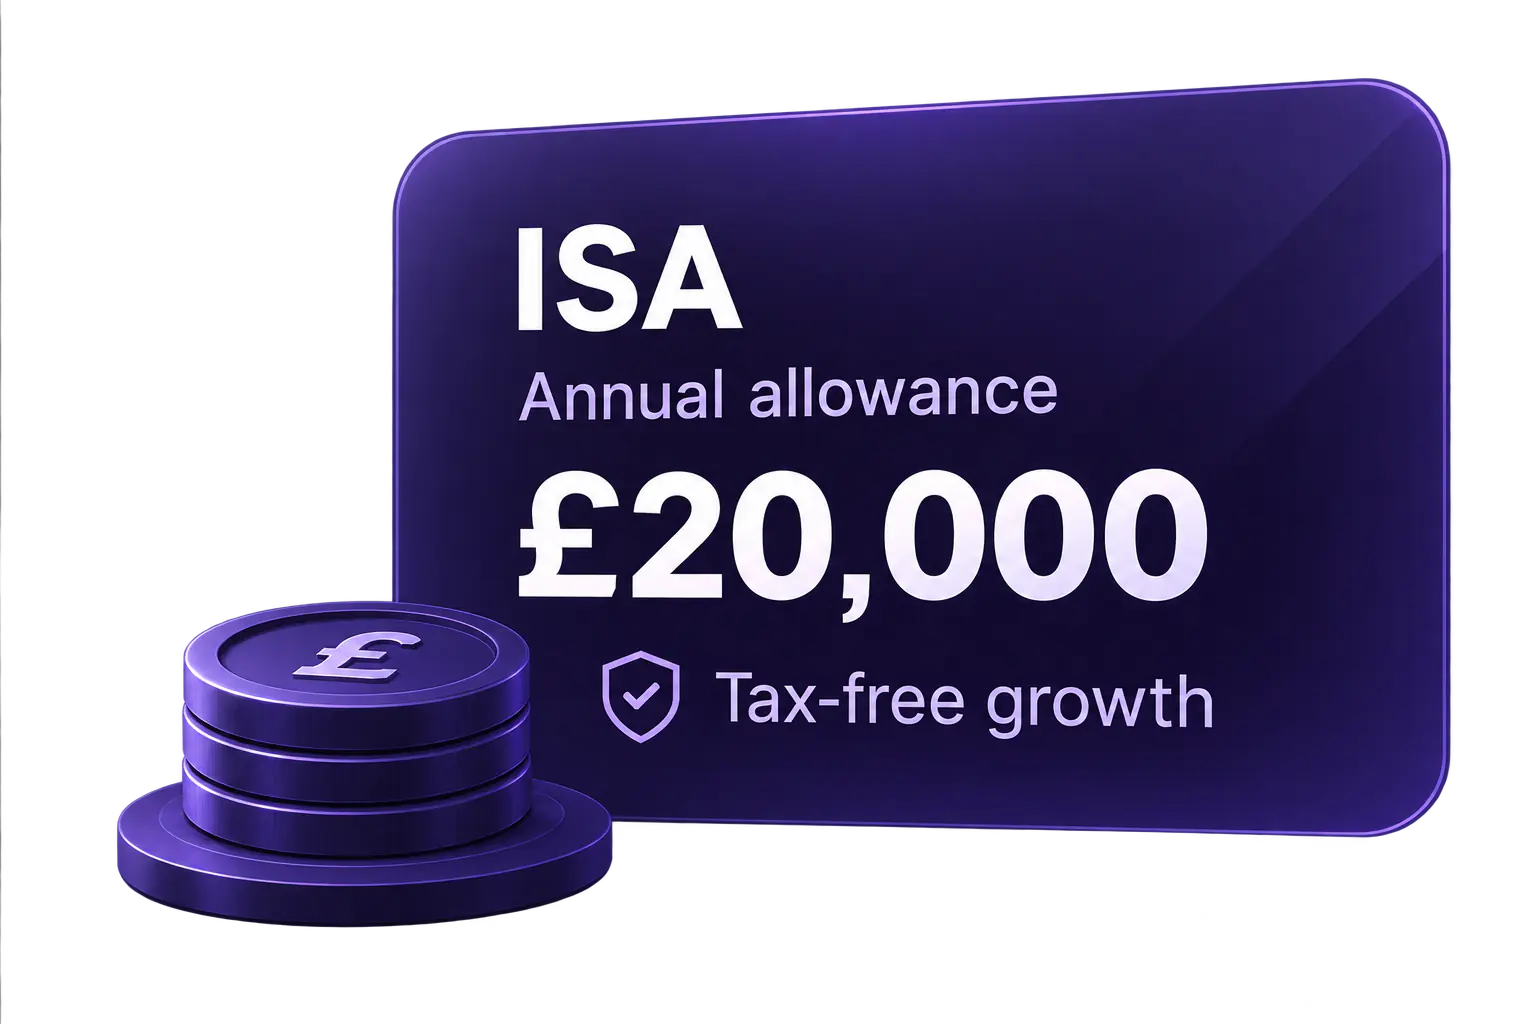
The government has announced new ISA rules, subject to legislation. The annual Cash ISA limit for under-65s will drop to £12,000 while the overall £20,000 ISA allowance stays intact — meaning more may look to Stocks & Shares ISAs to put their full allowance to work.
Key facts from 6 April 2027
| Before April 2027 | From 6 April 2027 | |
|---|---|---|
| Overall ISA limit | £20,000 | £20,000 unchanged |
| Cash ISA (under 65) | £20,000 | £12,000 |
| Cash ISA (65 and over) | £20,000 | £20,000 unchanged |
| Stocks & Shares ISA | Within £20,000 limit | Within £20,000 limit unchanged |
| Interest on cash in non-Cash ISAs | Tax-free | 22% charge 1 |
| Transfer S&S ISA → Cash ISA | Allowed | Not permitted for under-65s |
1. From 6 April 2027 the government has said that interest earned on cash held inside a non-Cash ISA will carry a 22% charge, paid to HM Revenue & Customs by the ISA manager rather than by you. You will not need to declare anything, and your Personal Savings Allowance is unaffected. These measures were announced at the Autumn Budget 2025 and remain subject to legislation. Source: HM Revenue & Customs, ISA reform 2027 anti-circumvention rules factsheet.
Why is the government making this change?
What does this mean for Stocks & Shares ISAs?
Can a Stocks & Shares ISA still hold cash-like investments?
Can I transfer from a Stocks & Shares ISA to a Cash ISA?
What does not change?
Fees compound. So does saving them.
A percentage fee scales with your balance, so the bigger you get, the more you pay. Drag the numbers to see what a flat fee keeps in your pocket — and where it doesn't.
Up to the £20,000 annual ISA allowance.
An assumption you choose, not a forecast. A percentage charge is taken from the value of your pot, so a higher assumed return increases the amount that charge collects.
more in your pocket with Investwizz over 20 years, driven by less paid in fees, compounded.
Break-even is around £19,980 invested: below that a low-cost option can be cheaper; above it, our flat fee pulls ahead.
Your capital is at risk. The value of your investments may fall as well as rise and is not guaranteed. This is not financial advice.
Comparison methodology
Illustrative projection assuming 5.775% gross annual growth and a 0.25% fund cost applied equally to both options; the comparison platform charges the percentage you select on your average balance each year, while Investwizz charges a flat £9.99 a month. Percentage rates are typical category ranges and may not reflect every provider, tier or product. Real returns will differ and could be negative; this is not a guaranteed outcome and past performance is not a guide to future results. The cash reference assumes around 1.31% (variable).
See your plan before you pay a penny.
Get the app and build a free starting plan around your goal, your comfort zone and your real numbers. It takes a few minutes, and you only invest when you're ready.
Questions before you start? Talk to our UK team →
Free to download. Capital at risk: the value of your investments can go down as well as up, and you may get back less than you invest.